Planning to apply for a personal loan, auto loan, mortgage, or other financing in the USA? One of the smartest things you can do before submitting an application is review and improve your credit profile. A strong credit history may help you qualify for better loan terms, while a weaker credit profile can make borrowing more expensive.
If you are wondering how to improve your credit score before applying for a loan, the good news is that several practical steps can help. Although there is no guaranteed way to increase your score overnight, responsible credit habits can make a difference over time.
Your credit score is one factor lenders may consider when evaluating a loan application. Different lenders use different criteria and credit-scoring models, so there is no single score that guarantees approval.
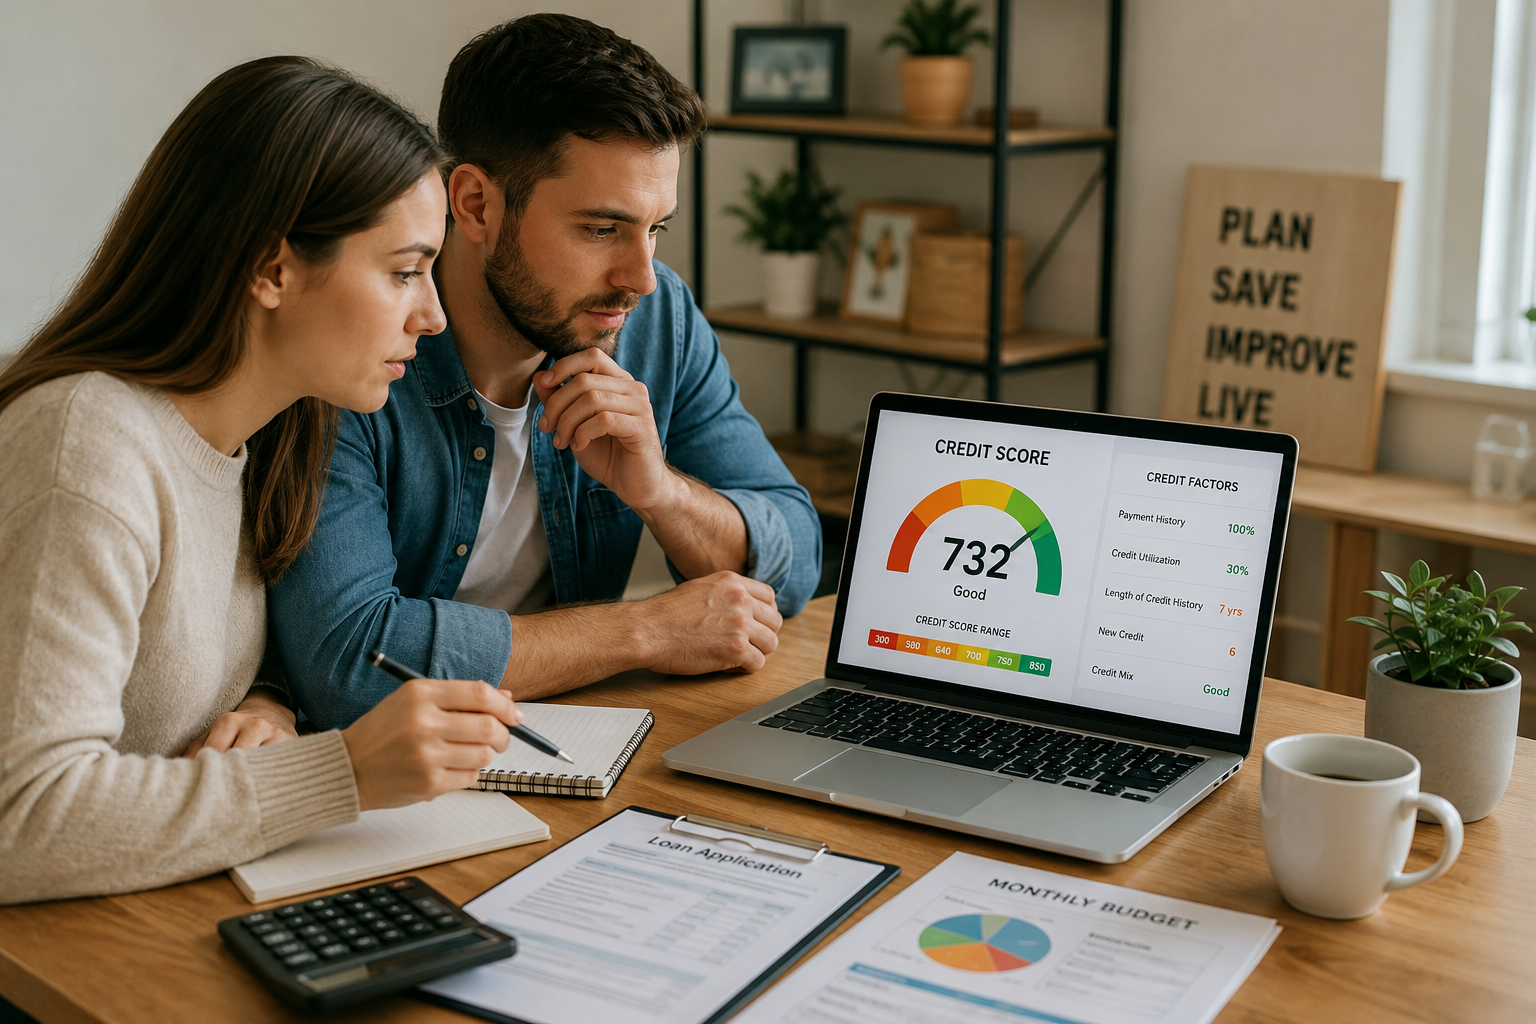
FICO Scores, for example, are generally based on five major categories: payment history, amounts owed, length of credit history, new credit, and credit mix. Payment history and amounts owed are the two largest categories in the standard FICO scoring model.
A better credit profile may help you access more borrowing options and potentially more favorable interest rates. However, lenders may also consider income, existing debts, employment information, the type of loan, and other factors.
Before applying for a loan, review your credit reports carefully. Look for accounts, balances, payment histories, and credit inquiries that you recognize.
Pay particular attention to potentially inaccurate information, such as:
* Accounts that do not belong to you
* Incorrect account balances
* Wrong payment history
* Duplicate accounts
* Incorrect personal information
* Unexpected collection accounts
Your credit report contains information that can be used to calculate credit scores, so identifying inaccurate information before a loan application can be an important preparation step.
If you find an error, investigate the appropriate dispute process with the credit reporting company and the company that provided the information.
One of the most important ways to improve your credit score is to make payments on time.
Payment history represents approximately 35% of a typical FICO Score calculation, making it the largest scoring category.
To avoid missed payments, consider setting up:
* Automatic payments
* Calendar reminders
* Text or email alerts
* A monthly bill-payment budget
If you already have late payments, focus on bringing overdue accounts current and maintaining a consistent record of on-time payments going forward.
Credit utilization is another important part of your credit profile. It generally refers to how much of your available revolving credit you are using.
For example, if your credit card limit is $10,000 and your balance is $4,000, your utilization on that card is 40%.
FICO identifies amounts owed as approximately 30% of a typical FICO Score calculation, and credit utilization is an important component of this category.
Before applying for a loan, consider paying down high credit card balances when your budget allows. Lower balances can reduce your credit utilization and may help strengthen your overall credit profile.
If you are preparing for a major loan application, think carefully before opening several new credit accounts.
Applications for new credit can result in hard inquiries, depending on the lender and application process. FICO also considers new credit as one of its scoring categories.
Instead of applying everywhere, research lenders first and understand their general eligibility requirements.
The length of your credit history is another factor used in FICO scoring. It represents approximately 15% of a typical FICO Score calculation.
If you have an older credit account that you rarely use, don't automatically close it simply because you are preparing for a loan. Closing an account can change your available credit and other aspects of your credit profile.
Your credit score is not the only thing lenders may examine. Existing debt and income can also matter when a lender evaluates whether you can afford another monthly payment.
Before applying, calculate your monthly debt obligations and compare them with your gross monthly income. This is commonly known as your debt-to-income ratio (DTI).
Reducing unnecessary debt can make your overall financial situation healthier and may make it easier to manage a new loan payment.
There is no universal timeline for improving a credit score. Your results depend on your existing credit history and what information is currently being reported.
For some borrowers, reducing revolving balances may change their credit profile after updated information is reported. Rebuilding credit after serious payment problems can take considerably longer.
The most effective approach is to start preparing well before you need the loan.
Before submitting your application, consider these steps:
* Review your credit reports.
* Check for inaccurate information.
* Make all payments on time.
* Reduce high credit card balances when possible.
* Avoid unnecessary new credit applications.
* Review your existing debt.
* Calculate your debt-to-income ratio.
* Determine how much you actually need to borrow.
* Compare loan costs, including APR and fees.
* Make sure the expected monthly payment fits your budget.
Learning how to improve your credit score before applying for a loan can help you become a more informed borrower. Start by reviewing your credit reports, maintaining on-time payments, reducing credit card balances, limiting unnecessary applications, and managing existing debt responsibly.
Remember that a good credit score does not guarantee loan approval, and a lower score does not automatically mean you cannot qualify. Every lender has its own requirements and underwriting process.